
How to measure the success of India’s capex strategy
India’s capex push has strengthened infrastructure and supported investment. But physical assets alone are not enough. The success of India’s capex strategy will be measured by whether or not companies invest more, workers become more productive, and the economy creates more value. So, is capex delivering? See infographics for quick key insights.
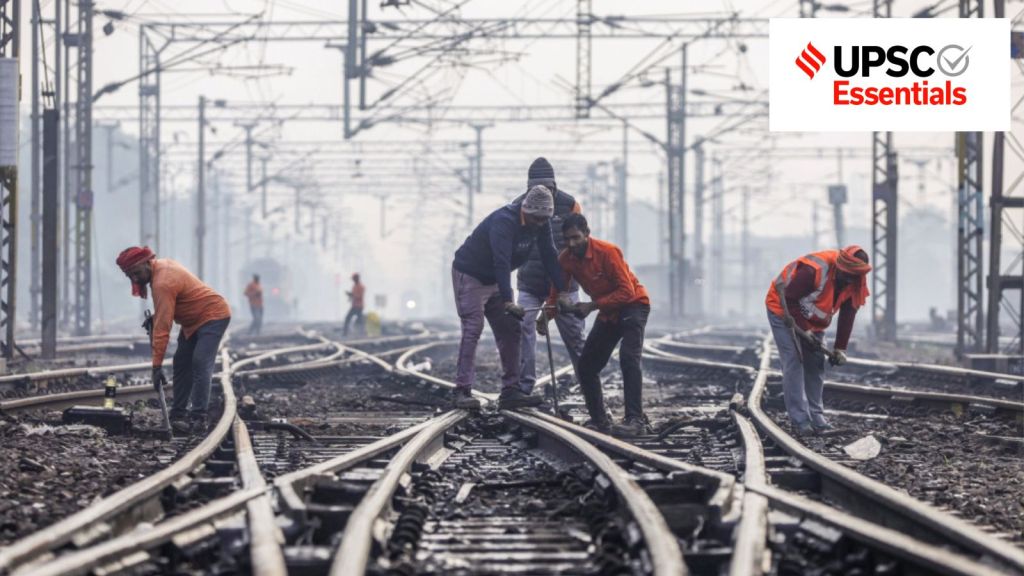 The Railways sector is a key component of the government's capex push. PTI
— Pushpendra Singh and Archana Singh
The marked rise in the Centre’s capital expenditure – 66% year-on-year to Rs 89,255 crore in June – means it’s now on track to meet its capex target of Rs 12.22 lakh crore for 2026-27. But why does capex matter? How can India’s public-investment push draw in private capital? How does it contribute to the country’s long-term growth?

Public investments driving India’s growth
Investments are crucial to growth, and India’s investment story is entering an important, if still incomplete, transition. During the last few years, especially after the pandemic, the Union Government led the investment push. Its capital outlay rose from 2.63 lakh crore in 2017-18 to a Budget Estimate of 11.21 lakh crore in 2025-26.
While the capex target for 2026-27 is 12.22 lakh crore, effective capital expenditure stands at 17.15 lakh crore. Effective capital expenditure includes both the Centre’s own capital spending and grants given to states and other agencies for creating capital assets.
India's Capex Push: Beyond the Budget Number
This is more than a rise in budget numbers. It shows a clear shift in spending priorities. The Economic Survey 2025-26 states that between FY20 and FY25, the share of capital spending in the total central government expenditure increased from 12.5% to 22.6%. Effective capex as a share of GDP also rose from about 2.6% to 4%, the survey said.
Public investment has therefore become an important pillar of India’s growth strategy. But the more important question now is whether this public capex cycle can create a sustained private capex cycle.
Public capex push crowding in private investment?
There are some encouraging signs. The National Statistical Office estimates private corporate capital expenditure on new assets at around 11.44 lakh crore in 2025-26. More importantly, nearly 65% of this investment is expected to come from firms’ own internal resources, while around 23% is financed through domestic debt.
This suggests that corporate balance sheets are healthier than they were during the earlier investment boom, when excessive borrowing contributed to the twin balance-sheet problem. There are other signs of improving investment conditions. Capacity utilisation reached 74.8% in the second quarter of 2025-26, above its pre-pandemic average of 72.9%. Capital goods imports also rose by 13.4% in the third quarter.
These indicators suggest that firms may be moving closer to the point where rising demand requires them to add fresh capacity. However, the private capex cycle remains uneven, and investment intentions do not always translate into completed projects. That is precisely why the quality of public investment matters.
Why capex matters
Not all government spending works in the same way. Revenue expenditure largely finances current obligations such as salaries, pensions, subsidies, interest payments, administration and routine programmes. In comparison, capital expenditure creates or improves assets such as highways, railway lines, power systems, irrigation networks, machinery and digital infrastructure.
But the distinction is not always so simple. A school building is capital expenditure, but teachers are paid through revenue expenditure. A hospital may be a physical asset, but without doctors, nurses and medicines, it cannot deliver better healthcare.
So, revenue expenditure is not necessarily unproductive, and capital expenditure is not automatically productive. An airport with few passengers or an industrial park without firms may create an asset on paper, but generate little economic value. The question is not simply whether spending is capital or revenue, but what that spending creates.
Well-planned capex can have a wider economic impact. A railway corridor, for example, creates demand for steel, cement, machinery and labour during construction. Once operational, it can lower freight costs, reduce travel time and improve access to markets. This is the capex multiplier.
In this way, capex works twice: it supports demand today and raises the economy’s productivity tomorrow.
Can public capex ‘crowd in’ private investment?
The central government’s infrastructure push via capex has led to strong gross fixed capital formation (GFCF) growth. GFCF is another important part of this story, which measures investment in factories, machinery, buildings and infrastructure. In 2025-26, it stood at about 32.3% of GDP. For a developing economy, this matters because sustained growth requires continuous expansion of productive capacity.
Public capex can also ‘crowd in’ private investment. A firm is more likely to build a factory when electricity is reliable, roads are better, ports are efficient and digital connectivity is strong. A highway can attract logistics and manufacturing. A freight corridor can lower transport costs. Better telecom networks can support digital services and data centres. This is why public investment can create the foundation for private investment.
In 2024-25, the centre spent around 2.85 lakh crore on roads and highways, 2.52 lakh crore on railways and 1.72 lakh crore on defence-related capex. Such spending can lower costs and create opportunities for private firms.
The Production-Linked Incentive (PLI) schemes provide another example. By September 2025, they had attracted more than 2 lakh crore in investment and supported incremental production and sales of over 18.7 lakh crore. The large lesson is simple: public capex works best when it creates an ecosystem for private investment, not just an isolated asset.
The next capex frontier
India’s next investment cycle cannot be built only on roads, railways and ports. Future growth will also depend on digital infrastructure, artificial intelligence, semiconductors and research capacity.
The meaning of infrastructure itself is changing. India’s digital public infrastructure has shown that shared platforms can lower transaction costs, widen access and help businesses scale. AI can deepen these gains by predicting machine failures, optimising freight, improving crop decisions, accelerating medical research, and making public services more responsive.
Semiconductors offer an even larger ecosystem opportunity. A chip plant is not simply another factory. It creates demand for engineers, precision equipment, specialised chemicals, design capabilities, testing laboratories, and advanced materials. But the benefits of technology capex depend on building capabilities.
India needs to avoid confusing subsidised capacity with technological capability. Building chip plants while continuing to import much of the equipment, intellectual property and expertise may increase production without creating the foundation for deeper technological capabilities. Manufacturing investment, therefore, needs to be accompanied by investment in R&D, universities, laboratories, design tools, and technical skills.
The ambition should not merely be to manufacture technology in India, but to design, improve and increasingly own that technology.
Can capex be the solution to every growth problem?
However, capex is not a solution to every growth problem. The first constraint is fiscal. For 2026-27, interest payments are budgeted at around 14.04 lakh crore, while the fiscal deficit is estimated at 16.96 lakh crore, or 4.3% of GDP. Borrowing can support productive investment, but it also creates future obligations and can reduce fiscal space for health, education and other priorities.
The second challenge is implementation. A budget allocation does not automatically become a productive asset. In 2025-26, capital expenditure was reduced from 11.21 lakh crore to about 10.96 lakh crore. Land acquisition, approvals, litigation and weak coordination can delay projects and increase costs.
The third challenge is private investment. Crowding-in is possible, but it is not automatic. Firms invest when they see demand, policy stability and reasonable returns. Better infrastructure helps, but it cannot by itself create business confidence or market demand.
Need to build capabilities, not just assets
India’s capex push has strengthened infrastructure and supported investment. But the next phase should not be judged only by the size of the allocation. A budget allocation is an intention. Spending is an input. A productive asset is the real outcome.
The test for public investment should therefore be straightforward: What has become faster, cheaper, more reliable or technologically possible because of this spending? A road should lower logistics costs. A railway should connect firms and markets more efficiently. Digital infrastructure should reduce transaction costs. AI investment should raise productivity. Semiconductor support should build domestic capabilities and supply chains.
But physical assets alone are not enough. Factories need skilled workers, semiconductor plants need engineers, and AI needs researchers. This is why capital expenditure and spending on education, health and skills must complement each other. What matters, therefore, is not simply the volume of public expenditure but its quality, composition and capacity to generate larger economic benefits.
India needs to build more, but it also needs to build better. The success of its capex strategy will be measured not simply by how much concrete is poured, but by whether firms invest more, workers become more productive, and the economy creates more value.
High-quality capex converts public money into productive capability. Poor-quality capex risks converting borrowed money into underused assets. Therefore, India’s approach to public investment needs to prioritise projects that raise productivity and sustain growth.
Post read questions
1. Public investment can crowd in private investment only when supported by adequate demand, policy certainty and productive capacity. Analyse.
2. India’s infrastructure push can raise potential growth only when accompanied by investment in human capital and technological capabilities. Discuss.
3. Can fiscal constraints limit the sustainability of India’s public-capex-led growth strategy? Illustrate.
4. India’s public investment strategy needs to evolve from asset creation to capability creation. Discuss with reference to digital infrastructure, semiconductors and artificial intelligence.
(Pushpendra Singh is an Assistant Professor of Economics at Somaiya Vidyavihar University, Mumbai. Archana Singh is Assistant Professor of Gender and Economics at the International Institute for Population Sciences, Mumbai.)
Share your thoughts and ideas on UPSC Special articles with ashiya.parveen@indianexpress.com.
Click Here to read the UPSC Essentials magazine for August 2026. Subscribe to our UPSC newsletter and stay updated with the news cues from the past week.
Stay updated with the latest UPSC articles by joining our Telegram channel – IndianExpress UPSC Hub, and follow us on Instagram and X.

 Share


