6 min readMumbaiUpdated: Aug 28, 2026 10:25 AM IST
The National Company Law Tribunal’s latest order in the personal insolvency proceedings against Zee Group founder Subhash Chandra has produced an unexpected outcome: creditors will receive just Rs 6.5 crore under the approved repayment plan.
Chandra said the total claim against him as a personal guarantor in the personal insolvency proceedings is only Rs 3,992 crore by the objectors of the plan, and not Rs 22,000 crore. Passed on Tuesday (August 25), the order yet again raises fundamental questions about the personal insolvency framework and the extent to which creditors can be compelled to accept an almost microscopic recovery.

The big haircut
Against the claim of Rs 3,992 crore, Subhash Chandra’s approved repayment plan provides for only Rs 6.5 crore. The difference represents claims that will not be recovered under the plan. “Lenders are effectively being left with very little,” said a banking source.
The scale of the write-down makes the case an unusually stark test of India’s insolvency regime. The central question is not merely whether creditors approved the plan, but whether such an extreme recovery can be justified when the amount owed runs into tens of thousands of crores.
What Subhash Chandra says
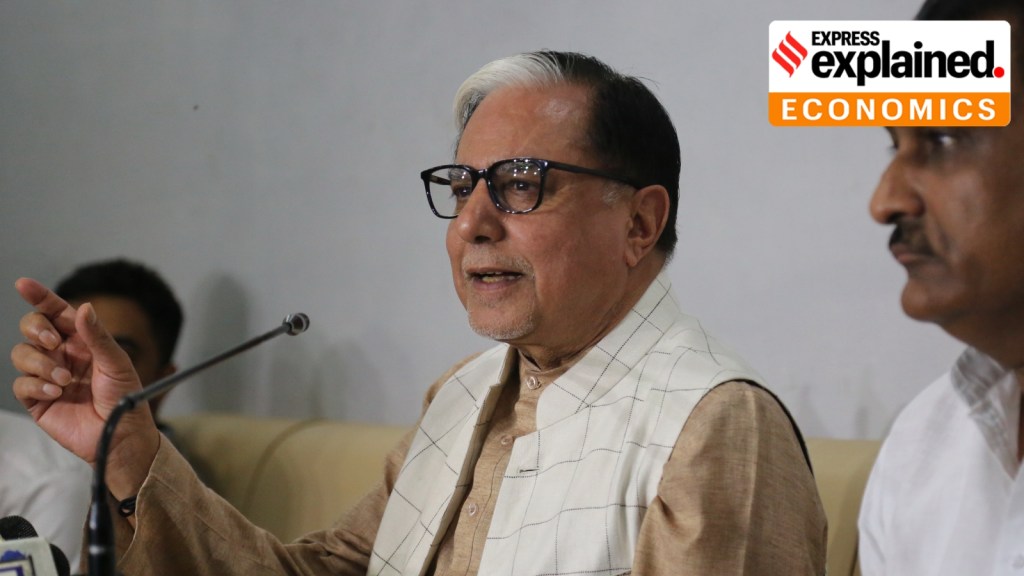
In a press statement issued on Thursday, Subhash Chandra’s office said he has not borrowed any money from any lender. “Chandra is only a personal guarantor. Total claim against Subhash Chandra as a personal guarantor, in the personal insolvency proceedings is only Rs 3,992 crore by the objectors of the plan and not Rs 22,000 crore,” the statement said.
“Out of which, also a claim of Rs 620 crore settled and further Rs 1,063 crore offered to be paid by the borrower entities. The borrowing entities for whom Chandra has provided personal guarantees have till date repaid Rs 43,000 crore. The borrowing entities have assured to settle any other amount which might have left,” it said.
“He (Subhash Chandra) declared his total assets stood at Rs 39.08 crore which he declared in the Parliament of India in 2016, which is a public record. How could a bank take/accept his net worth of Rs 45,888 crore in 2017?” the statement said.
Story continues below this ad
“He paid from his personal account few times the salaries of employees when the borrowing companies could not pay salaries. Hence his personal net worth came down to Rs 31.79 crore in 2024 from Rs 39.08 crore in 2016. This includes one residential house worth close to Rs 25 crore. Hence, he can pay what he has with him and basis which the Rs 6.5 crore repayment plan has been arrived,” the statement added.
Personal guarantee
The proceedings concern personal guarantees given by Chandra for borrowings of Essel Group-linked companies.
When a promoter gives a personal guarantee for corporate loans, the lender can, subject to the applicable legal process, pursue the guarantor when the underlying borrower defaults.
Chandra’s insolvency proceedings were initiated in 2024 following a petition by Indiabulls Housing Finance. The case, therefore, goes beyond Zee Entertainment Enterprises. It concerns Chandra’s personal liability arising from guarantees linked to corporate debt. It should not be confused with separate corporate insolvency proceedings involving companies associated with the Essel Group, or with regulatory proceedings involving Zee Entertainment and its executives.
Breaking the deadlock
Story continues below this ad
The August 25 order was not the result of a straightforward, unanimous decision. A two-member NCLT bench had earlier delivered a split verdict on the repayment plan.
With the members divided, Nilesh Sharma, judicial member of the NCLT, acted as the third member to resolve the disagreement.
The tribunal concluded that the approved repayment plan could provide a better outcome than simply pushing the matter into bankruptcy. (NCLT website)
The third member ultimately sided with approval of the repayment plan. Creditors had mounted strong objections, particularly over the extraordinarily low amount they were being offered. But the tribunal concluded that the objections did not provide sufficient legal grounds to reject the plan.
The tribunal examined the available financial information and concluded that the approved repayment plan could provide a better outcome than simply pushing the matter into bankruptcy. In other words, the logic was pragmatic: Rs 6.5 crore may be better than an even smaller recovery from liquidation or bankruptcy.
Creditors objected
Story continues below this ad
The creditors’ objections centred on the extraordinarily low recovery and questions surrounding Chandra’s financial position. Creditors also questioned whether the debtor’s assets and financial affairs had been examined deeply enough, including whether a forensic investigation should have been conducted.
The tribunal, however, did not accept the argument that a forensic investigation was an essential precondition for approving the repayment plan. The NCLT also emphasised the importance of the commercial decision of creditors. Where creditors have voted on a plan in accordance with the Insolvency and Bankruptcy Code, the tribunal does not ordinarily substitute its own commercial assessment for that decision.
The repayment plan had secured the required support from creditors, with the plan reportedly receiving about 80.81% of the voting share. Once the requisite majority of creditors approves a repayment plan and the tribunal sanctions it, individual dissenting creditors cannot simply walk away from the process and demand a different settlement.
Lesson for lenders
The case exposes a reality of lending to promoters. A bank may have a claim running into thousands of crores and still recover virtually nothing if the underlying assets and enforceable guarantees do not support the debt. A personal guarantee can strengthen a lender’s position, but it is not the same thing as cash sitting in a bank account. Its ultimate value depends on the guarantor’s legally available assets and the insolvency process.
Story continues below this ad
For banks and financial institutions, the case is therefore a warning about the quality — rather than merely the existence — of promoter guarantees.
The order does not mean that Chandra has been declared free of all legal or regulatory scrutiny. Nor does it extinguish or decide unrelated proceedings involving Zee Entertainment or other Essel Group entities. It is also separate from SEBI’s proceedings involving Zee Entertainment and Punit Goenka.
For creditors, that is an almost total destruction of value. For the insolvency system, it is a stark demonstration of the difference between the amount a lender is owed and the amount it can realistically recover.




 The tribunal concluded that the approved repayment plan could provide a better outcome than simply pushing the matter into bankruptcy. (NCLT website)
