
Inside Tata boardroom feud: How Noel Tata, N Chandrasekaran fell out
Natarajan Chandrasekaran’s exit did not happen suddenly — it followed six months of uncertainty over his reappointment and differences with Tata Trusts Chairman Noel Tata. So, what explains the breakdown between the two?
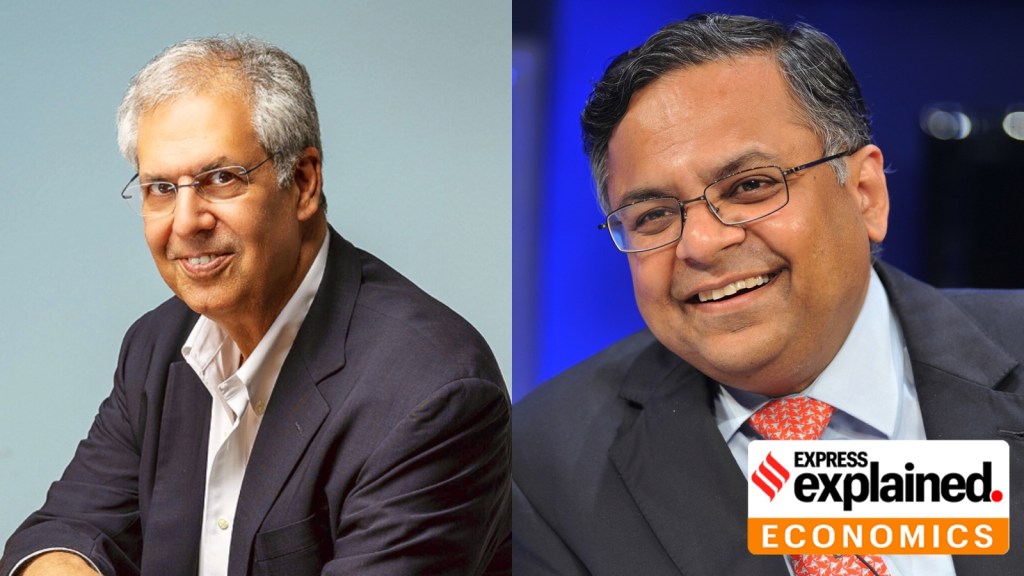 Tata Trusts Chairman Noel Tata and Tata Sons Chairman Natarajan Chandrasekaran.
Natarajan Chandrasekaran’s decision not to seek another term as Chairman of Tata Sons brings to an end, at least in its present form, a leadership chapter that began in 2017. But his exit did not happen suddenly. It followed six months of uncertainty over his reappointment, differences with Tata Trusts Chairman Noel Tata, questions over the performance of some unlisted businesses, and a wider governance tussle within the Tata Trusts.
Tata Trusts are the majority shareholder of Tata Sons which, in turn, is the principal holding company of the $180-billion Tata group. What explains the split between the two power centres — Chandrasekaran at Tata Sons and Noel Tata at Tata Trusts?

Chandra pre-empted trustees’ move?
The proposed August 13 meeting of Tata Trusts, followed by the August 18 AGM of Tata Sons, could have set the stage for Chandrasekaran’s — Chandra as he’s known among colleagues — exit from the group’s top leadership.
According to the plan being discussed among some trustees, the August 13 meeting was expected to consider opposing or withholding an extension of Chandrasekaran’s tenure. Any such decision could then have been taken up formally at the Tata Sons AGM on August 18, potentially putting the issue of his continuation squarely before shareholders, said a Tata group source.
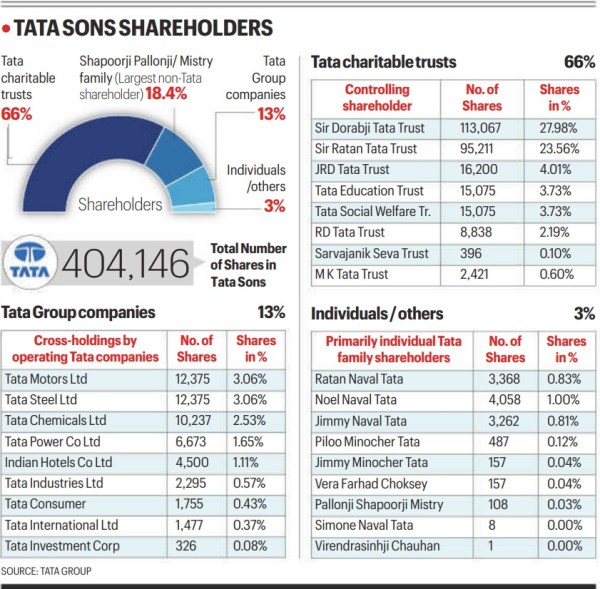 Tata Sons shareholders
Chandrasekaran appears to have anticipated the move and chose to act before the formal process to deny him an extension could be set in motion. Rather than wait for the trustees — read Noel Tata — to take a position and risk a potentially public and contentious showdown at the AGM, he is understood to have preferred to step down on his own terms.
Just weeks ago, the Tata Sons AGM notice had proposed his name for reappointment as a Director. “That was a procedural move,” said a Tata source.
The sequence of events suggests that his departure was not simply a routine leadership transition, but came amid a growing contest over whether his tenure should be extended. His decision to move first may have been aimed at retaining control over the timing and manner of his exit, rather than allowing the trustees’ decision — and potentially an AGM confrontation — to determine his fate.
February 24: Difference out in the open
The first public sign of trouble came on February 24, when the Tata Sons board deferred a decision on extending Chandrasekaran’s tenure for a third term. His existing tenure runs until February 2027, and the proposal was for another five years.
The issue was not simply whether Chandrasekaran had performed well. The deeper question was whether the Tata Trusts, which collectively own about 66% of Tata Sons, were comfortable with his continuation. Noel Tata raised concerns about losses at some group companies, capital deployment and the future structure of Tata Sons. Keeping Tata Sons unlisted was among the conditions being discussed.
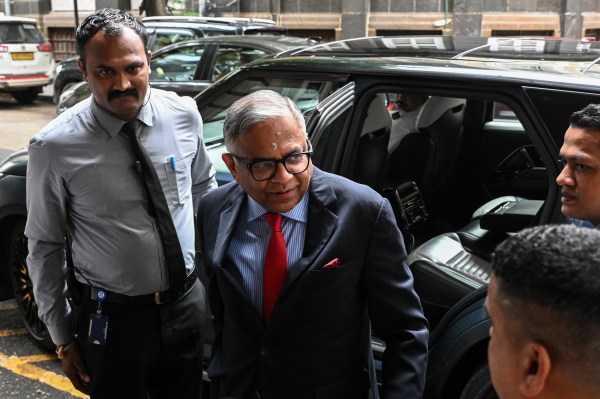 N Chandrasekaran, the chairman of Tata Sons, enters Bombay House in Mumbai announced his resignation, in Mumbai on August 13. Sankhadeep Banerjee.
Four directors were then ready to vote in support of Chandrasekaran. Chandrasekaran himself said he proposed postponing the decision, and later explained that the February proposal did not receive unanimous support.
He said one board member did not support his reappointment and that, in the absence of unanimity, he chose to defer the matter. This was significant because the Tata Group has historically placed considerable emphasis on consensus, particularly on major leadership questions. Once the February decision was deferred, the uncertainty remained unresolved for six months.
Trust factor
There was a growing view within the group that Noel Tata never fully trusted Chandrasekaran, particularly when it came to the future direction of Tata Sons and the preservation of the group’s traditional culture. Some in the group also felt that Chandrasekaran was not doing enough to keep Tata Sons private or to address the mounting losses at some of the group’s unlisted companies.
The differences were seen as being rooted not just in strategy, but also in philosophy. Chandrasekaran, according to people familiar with the thinking inside the group, may have been more open to the idea of eventually listing Tata Sons if he were not its chairman. Noel Tata and some of the group’s older hands, however, are believed to have preferred keeping the holding company unlisted, arguing that this would give the group greater flexibility and help preserve the culture, values and heritage associated with the Tata name.
“Chandra would have supported the listing of Tata Sons had he not been the chairman. Noel and the old-timers want the firm to remain unlisted and preserve the culture and heritage,” said a source familiar with the thinking within the Tata group.
The issue, therefore, was seen by some as extending beyond the question of a potential listing. It reflected a broader tension between the demands of corporate governance and capital allocation on one hand, and the desire to protect the Tata group’s long-established structure, culture and legacy on the other.
Losses at unlisted companies, salary surge
Tata Group’s market capitalisation has more than tripled over the past nine years, rising to around Rs 27 lakh crore. But the expansion in market value has been accompanied by mounting losses at some of the group’s major unlisted businesses, raising questions about the financial performance of companies that do not directly contribute to the group’s listed-market valuation.
The losses of eight unlisted Tata companies stood at Rs 33,538 crore in FY26. Air India accounted for the largest share of these losses, with its annual loss doubling to Rs 22,238 crore. Tata Digital, another key unlisted business that houses the group’s digital ambitions, reported a loss of Rs 4,974 crore during the year.
The widening losses at these businesses became a major point of contention between Noel Tata and Chandrasekaran. While the group’s listed companies have created substantial shareholder value and helped push Tata Group’s combined market capitalisation to unprecedented levels, the performance and capital requirements of some of its unlisted ventures have remained a significant concern. Noel Tata raised questions about these losses.
At the same time, Chandrasekaran’s remuneration has risen sharply during his tenure as chairman of Tata Sons. His total remuneration increased nearly threefold to Rs 158.66 crore in FY26, from Rs 55.11 crore in FY18. Cumulatively, his remuneration since FY18 has crossed Rs 900 crore.
The sharp increase in remuneration comes against the backdrop of a period in which the Tata Group has undertaken an aggressive expansion and transformation of several businesses, including aviation, digital services and retail ventures. While supporters could point to the substantial increase in the group’s market value and the scale of the businesses being overseen, the rise in executive pay alongside mounting losses at unlisted companies has also intensified scrutiny over capital allocation, accountability and governance at Tata Sons.
The listed portfolio has delivered significant value creation, but the performance of the group’s unlisted companies remains a key measure of whether that growth has translated into broader financial returns for the Tata conglomerate.
Tata Trusts was a house divided
The dispute between Noel Tata and Chandrasekaran cannot be understood separately from the tensions within Tata Trusts. Noel Tata became chairman of Tata Trusts after Ratan Tata’s death in October 2024 with the support of all trustees. The Trust is an important factor because they control about two-thirds of Tata Sons and exercise enormous influence over the group in nominating Directors and finding a successor.
Follow our daily newsletter so you never miss anything important. On Wednesday, we answer readers' questions.
Soon after Noel Tata’s takeover, differences emerged among trustees over governance, board representation and decision-making. Mehli Mistry, a close associate of Ratan Tata, eventually lost his position on the boards of the two principal trusts. Mistry later questioned governance arrangements and potential conflicts of interest before the Maharashtra Charity Commissioner. There were also disagreements involving Venu Srinivasan and Vijay Singh over trustee and Tata Sons board positions. Srinivasan, though a trustee, approached the Charity Commissioner over the composition of trustees at Sir Ratan Tata Trust.
These developments showed that the post-Ratan Tata era was not characterised by the same institutional cohesion that had prevailed earlier.
“There was speculation attributing the dispute to ‘Parsis versus non-Parsis’ or ‘old guard vs North- South’ and the ‘group slipping out of the hands of Parsis’. Such descriptions have appeared in anonymous accounts of the internal conflict, but they are not established explanations for Chandrasekaran’s departure. The documented issues concern governance, trustee appointments, board representation, Tata Sons’ listing and business performance,” said a source.

George Mathew is an Associate Editor with The Indian Expre... Read More
 Share


