The Southwest monsoon’s revival in July, in the face of a strengthening El Niño, has helped considerably narrow the gap in area sown under kharif crops this season relative to last year’s coverage.
The Agriculture Ministry’s data shows that Indian farmers had planted only 350.85 lakh hectares (lh) area in the current kharif (monsoon) season till July 6, which was 20.8% below the 442.80 lh sown during the same period of 2025.
These acreage gaps were even higher for oilseeds (39.3%), pulses (21.8%) and cotton (23%). A previous explained column had pointed out that the combined value of India’s imports of the three commodities was close to $25 billion in 2025-26 (April-March) and how El Niño could push this further to a new high in the current fiscal.
The above lag in sowings was courtesy of a poor start to the monsoon season (June-September). Rainfall during June for the country as a whole was 38% below the normal long-period average (LPA) for the month.
June usually witnesses around three low-pressure systems (LPS) that bring rain and are active over 11 days of the month. This June was an anomaly, with not a single LPS being formed. That made it the sixth driest June in India since 1901. The previous five years to have registered lower June rainfall were 2014, 2009, 1926, 1923 and 1905.
Significantly, the deficient June rainfall was despite El Niño only emerging and being in a weak-to-moderate phase that month.
The July turnaround
In July, El Niño intensified into a moderate-to-strong event.
Yet, this month recorded four LPSs, as against the normal three. And since these systems moved slowly with longer durations, the number of LPS-affected days were about 24 (normal is 14). As a result, all-India rainfall in July was 2.4% above the LPA. This was contrary to the India Meteorological Department’s (IMD) forecast of “most likely to be below normal (<94% of LPA)” rains for the month.
The monsoon’s turnaround in July and the cumulative rainfall deficit for the season easing to 11.8% as on August 10, notwithstanding a strengthening El Niño, has spurred kharif sowings. The 967.92 lh area covered till August 7 was only 1.8% lower than the progressive acreage during the corresponding period of last year
Moreover, the sowing gap has also reduced to 1.8% in pulses and 0.4% in cotton, while exceeding last year’s levels for oilseeds, particularly groundnut and sesamum (see accompanying table).
 Kharif area as of August 10.
“The rains during the third and fourth weeks of July have boosted sowings and also been amrit-varsha (life-rejuvenating) for the already-sown crops that were facing moisture stress. Without these showers, their vegetative growth (development of roots, stems and leaves) would have got affected,” said Nitin Kalantri, a leading dal (split pulses) miller from Latur in Maharashtra.
The area sown under soyabean, too, has shown smart recovery. “Overall, the crop condition is normal to good. Healthy vegetative growth is being observed in most areas, with no major insect pest or disease incidence reported during field inspections,” according to D.N. Pathak, executive director of the Indore-based Soybean Processors Association of India.
The worst isn’t over
The kharif crops need rain during August and early September too, when they undergo flowering and grain/pod formation that ultimately translate into yields.
The IMD has predicted a fresh LPS to form over the north Bay of Bengal and adjoining West Bengal-Bangladesh coasts around August 13, which should sustain the monsoon’s present active phase at least till the third week of the month. The uncertainty is over what happens after that.
Most global weather agencies expect sea surface temperatures in the central and eastern Pacific Ocean off the coasts of Peru and Ecuador to keep climbing, before turning into a “very strong” El Niño during October-December. Further, the El Niño conditions may persist through the winter and spring months till March 2027.
There are two implications from this.
First, El Niño’s actual impact on rainfall and temperatures – i.e. for the warm ocean waters to alter atmospheric air and wind patterns – comes with a lag of 1-2 months and can play out over 5-6 months or more. To that extent, the worst from El Niño, in terms of suppressing rainfall, is still to come.
Second, if El Niño continues to intensify, and given that it is known to raise temperatures as well, the real hit would be to the ensuing rabi or winter-spring crops. A relatively short and warm winter isn’t good for wheat, mustard or potato yields.
In short, even if kharif doesn’t turn out as bad as it was feared – especially after an extremely dry June – the uncertainly from El Niño on the rabi season remains.
Global price hardening
Meanwhile, the United Nations’ Food and Agriculture Organization’s (FAO) food price index has hit a three-and-a-half year high in July.
The index – a weighted average of world prices of a basket of food commodities over a base period value (taken at 100 for 2014-16) – touched 131.1 points last month, up 1% from July 2025 and the highest since the 131.4 of January 2023.
The rise is being attributed to the perfect storm from El Niño and the effects of recent heatwaves on crop yields in Europe, alongside renewed supply disruptions from conflicts in West Asia and Ukraine.
A closer look at the FAO index components, however, shows the increase to be largely vegetable oils-driven. At 195.7 points, the FAO’s vegetable oils index in July was 17.3% up year-on-year and the highest since June 2022 (see chart). The cereals index, at 113.8 points, was 6.9% higher than a year ago, while the dairy and sugar indices were actually down by 24.8% and 8% respectively. The meat index was up just 0.8% compared to July 2025.
Clearly, vegetable oil prices are the real concern for India now. Their firming up has mainly to do with diversion from food towards biofuel production. When international petroleum prices harden, as they have been of late, there’s added incentive to use palm, rapeseed and soyabean oil for making fatty acid methyl esters. The latter is a substitute for regular petroleum diesel.
On the positive side, the government has enough stocks of rice and wheat – 92.6 million tonnes (mt) on July 1, against a required minimum of 41.1 mt – and also pulses (over 4 mt). These stocks in public godowns can be offloaded in the open market to contain food inflation.

 School children enjoy themselves in the rain during the heavy showers in the capital New Delhi. (Express Photo by Tashi Tobgyal)

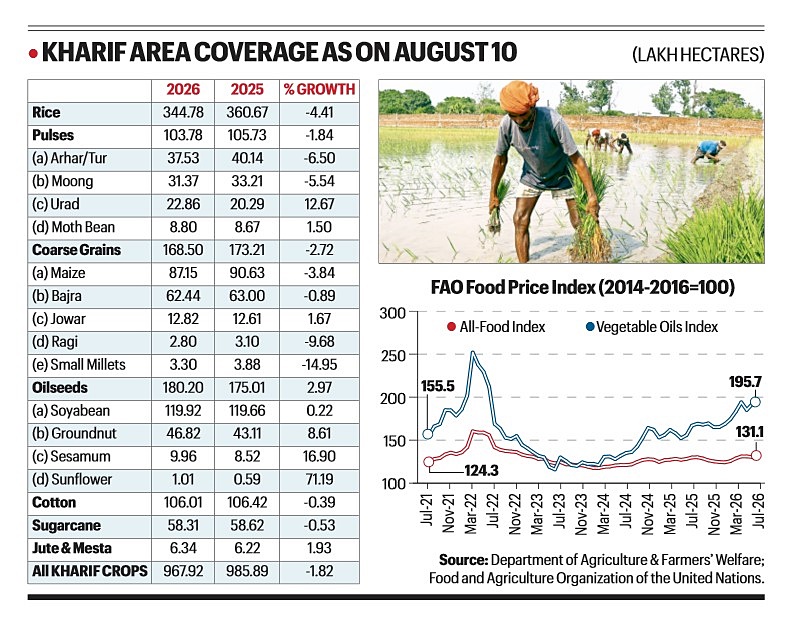 Kharif area as of August 10.

 Share


