As the India-United States trade deal looks set to be announced over the next few days, a new deal inked by the Donald Trump administration with Vietnam offers fresh pointers for how Washington DC is approaching these trade agreements.
One, the Vietnam deal shows that Trump is serious about tariffs, and that any belief that his administration plans to put off the tariff threats might be misplaced. The US Vietnam deal is clearly lopsided against the smaller, developing country, given that the US will impose a 20% tariff on Vietnamese goods entering the country while Vietnam has been arm twisted to drop all tariffs on American goods. For other countries too, including smaller nations, there is a strong likelihood of the deals being completely lopsided in favour of the US. Also, while the 20% rate is lower than the original proposal of 46% tariff on Vietnam, this rate is certainly higher than the 10% that was levied when the reciprocal tariffs were withdrawn. But there is a really big catch in the deal fineprint.

Two, the catch in this deal is that any goods that are transshipped through Vietnam to the US will face a double tariff of 40%. That is a move clearly aimed at one country only — China. A lot of Chinese components make their way to Vietnam and are integrated into goods that the South-East Asian country eventually ships to the US, and the rest of the world. For instance, Chinese fabrics are used in Vietnamese clothing, given that the latter does not really have a cotton or man-made fibre production base. Chinese components go into electronics that are assembled in Vietnam and sent abroad. A higher tariff rate on goods that are made and assembled in Vietnam, but include foreign components, is clearly a move aimed at targeting Chinese producers and potentially make them less competitive while using production bases such as Vietnam. Now, that is a template, which could be followed for other ASEAN countries that are increasingly being regarded by Washington DC as transshipment hubs for China. The broader message from this is perhaps that the Trump administration could continue to act tough on China. In both respects, this could be good news for countries such as India if they are able to wrangle better terms in their deals with the US. Vietnam is a competitor for India, and benefits greatly from the China alliance.
Third, the Vietnam deal shows that the pact seems to be centered on headline tariffs, even as they do not seem to really address the sectoral tariffs, which has been a key sticking point for countries such as Japan and South Korea, who were earlier seen as frontrunners to clinch early deals. Sectoral tariffs are an issue for India too. What the Vietnam deal likely shows is that there is still going to be a lot of fog even after a deal is clinched, especially with Asian countries that generally have multiple tariff lines and an array of tariffs.
Fourth, the big takeaway from this deal is that the tariff onslaught initiated by the US is likely to continue focusing on China.
Three buckets
With the July 9 deadline looming, which is just three-working days away, there are indications the about 20-odd countries that are in active talks with the Trump administration are eventually going to land up in three main buckets — the ones like possibly India, Taiwan and the European Union, which are likely to get a deal, just like the UK and Vietnam.
Others might get more time to negotiate, maybe another three months or so.
Then there’s going to be the third grouping of countries that are just going to get handed their tariff rate without any negotiation whatsoever.
Canada and Mexico are outside of these three categories, since the reciprocal tariffs were not slapped on them in the first place.
Meanwhile, the last word on the validity of the reciprocal tariffs is likely to come from the judiciary, since the matter is being heard in American courts.
India’s views
There are some implicit assumptions that New Delhi seems to be working with in its approach to a deal with Washington DC.
Despite President Trump’s vacillations on trade policy, there is confidence here that the administration in Washington DC will maintain a steady differential in tariffs between China and countries such as India. Precisely for that gap to be maintained, a deal, officials said, needs to be clinched by India. The Vietnam deal is being seen as a vindication of this view.
Also, while agriculture is a concern, as is the perceived arm twisting by the Trump administration on issues that are sensitive from an Indian point of view, there is a growing sense within an influential section of policymakers here that a deal for New Delhi is vital to keep the differential with China in place, especially since Beijing is also trying to strike a deal of its own. The question really is whether the Indian negotiators would have to settle for a limited early-harvest type of mini deal, or would they have to turn away from the negotiating table for now, let the July 9 deadline pass, and then rebuild efforts to bridge the gaps. A full-scale deal looks out of the question for now.
Second, there is now a realisation that cutting tariffs across segments, especially intermediate goods, might be a net positive for India. Also, while the redlines for India would include sensitive sectors such as dairy products and cereals, where agri livelihoods are at stake, there is now greater receptiveness within India’s policy circles to cut tariffs on some industrial goods, including automobiles, and some agri products of interest to the Amercians. Also, India has headroom to import more from the US, especially in three sectors — crude, defence equipment and nuclear, to manage Trump’s constant references to the trade gap.
Third, there is a growing view that the baseline tariffs are here to stay. So, effectively, what India would be negotiating for is a rate between 10% and 26 %. Prior to Trump’s taking over in January, the effective duty on India was just 4%, and there were virtually no non-tariff barriers. That number is now a thing of the past. What is more consequential is the effective duty on Chinese products on a landed basis across US ports in commodity categories where Indian producers are reasonably competitive. The net tariff differential with India, and how that curve continues to move, is of particular interest here, given the firm belief in policy circles here that Washington DC would ensure a reasonable tariff differential between China and India. This is, in turn, expected to tide over some of India’s structural downsides — infrastructural bottlenecks, logistics woes, high interest cost, the cost of doing business, corruption, etc.

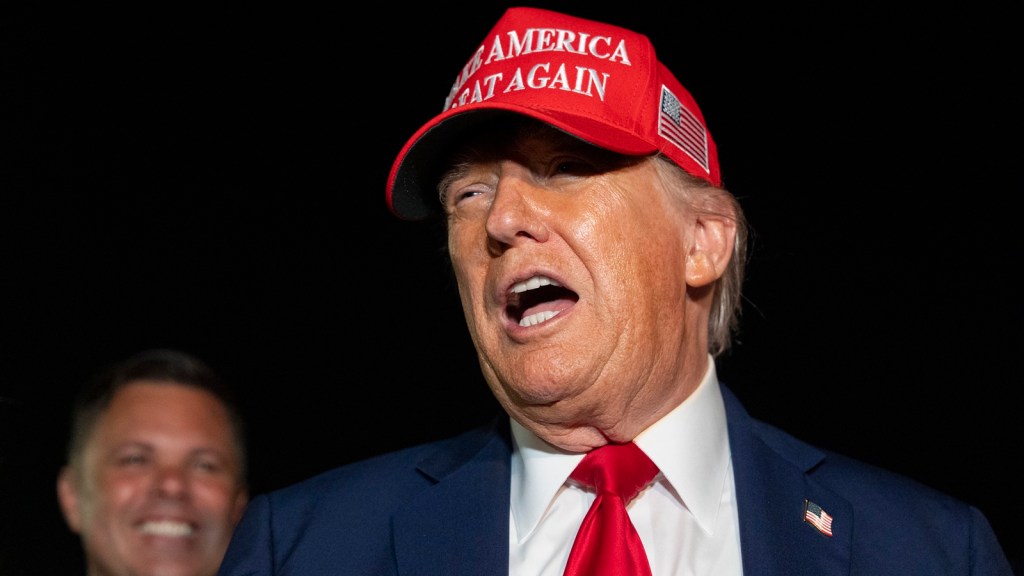 US President Donald Trump had announced the trade deal with Vietnam on July 3. (Photo: AP)


 Share


