The US Federal Reserve cut interest rates Thursday by 25 basis points (or one quarter of a percentage point), the second reduction of 2024, while continuing to signal that inflation is coming under control. The Fed’s move comes less than 48-hours after America elected Donald Trump as its next president.

Analysts have been predicting that borrowing costs in the US will fall further in the months ahead, but have warned that Trump’s impending tax cuts plans, tariff hike proposals and immigration control measures could stoke inflation and drive up government borrowing, thereby potentially driving a conflict with the American central bank. Interest rates on US debt have already surged this week, reflecting those concerns.
Powell said at Thursday’s briefing that it was too early to tell how the incoming administration’s agenda might impact the US economy. “It’s such an early stage – we don’t know what the policies are, we don’t know when they will be implemented,” he said. “In the near term, the election will have no effects on our policy decisions.”
Federal Reserve Board Chairman Jerome Powell speaks during a conference at the Federal Reserve in Washington on Thursday. (Photo: AP)
Trump’s potential conflict with the Fed
Powell was named chairman of the US Fed by Trump in 2017, but soon turned into a target of his criticism. Trump has said repeatedly he believes the US President has the right to air his views on Fed actions. He told Bloomberg earlier this year that he would let Powell serve out his remaining term, which ends in 2026, “especially if I thought he was doing the right thing”.
The Trump presidency is being viewed as being positive for American stocks, good for the dollar, but somewhat negative for treasuries with a risk of fiscal profligacy. For India, the Trump presidency could mean a challenge towards balancing its growth ambitions amid disruptions to supply chains, trade wars and tariff barriers and heightened forex volatility. Delayed cuts by the Fed would also impact the trajectory of the Indian monetary policy as the Reserve Bank of India may first try to resolve the uncertainties before undertaking any significant rate cut action.
While Trump’s promised tax cuts and tariff barriers could stimulate the American economy initially, analysts predict this could lead to higher inflation and could likely force the US Fed to end its rate-cutting cycle sooner than otherwise. That could have implications for the monetary easing plans of other countries, including India.
Impact of Fed rate cut
The Fed (and other central banks) influences employment and inflation primarily by using monetary policy tools to control the availability and cost of credit in the economy. The Fed’s primary tool of monetary policy is the federal funds rate, changes in which influence other interest rates — which in turn influence borrowing costs for households and businesses, as well as broader financial conditions.
When interest rates go down, it becomes cheaper to borrow — so, households are more inclined to buy more goods and services, and businesses have an incentive to borrow funds to expand operations, buy equipment, or invest in new projects.
Improved demand for goods and services pushes up wages, and helps rekindle the growth cycle. While monetary policy does not link directly or immediately to inflation and employment, monetary policy is a key factor in curbing runaway prices or stoking the growth impetus.
A cut in interest rates in the US could have a three-pronged impact:
📌 The difference between the US and other countries’ rates could widen — making countries such as India more attractive for currency carry trade. The lower the US rate, the higher the arbitrage opportunity, till the time that the rate-cut cycle starts in other economies as well.
📌 A lower rate signal by the Fed would also mean a higher impetus to growth in the US, which could be positive news for global growth, especially as China reels due to a real estate crisis and shows signs of slowing down.
📌 Lower returns in US debt markets could also trigger a churn in emerging market equities, improving foreign investor enthusiasm. There is also a potential impact on currency markets, stemming from inflows of funds.
The RBI last cut the repo rate by 40 bps to 4% in May 2020, when the Covid-19 pandemic led to a slowdown in demand, production cuts, and job losses. RBI has since hiked the repo rate by 250 bps to 6.5% in order to tackle runaway inflation (it has a mandate to keep inflation at 4%, with a cushion of 2% on either side). The next meeting of the RBI’s Monetary Policy Committee is scheduled for December 4-6.
China stimulus and BoJ hike
The other big external factor to watch out for is China, where the standing committee of the Standing Committee of the National People’s Congress, the executive body of the nation’s top legislature, convened in Beijing for a highly anticipated five-day meeting that began Monday. Once it gets over later Friday, the committee is expected to sign off on an economic stimulus package – the second such measure in a little over a month – that could end up directing more funds towards buying idle land and property, recapitalising banks, refinancing local-government debt and offering assistance to households.
Given Trump’s victory, and his threats of over 50% tariff on Chinese goods that could shave off, according to analysts, over two percentage points from China’s growth over the next year, Beijing could push a bigger stimulus package. Nomura anticipates the eventual scale of China’s fiscal stimulus package to reach 2-3% of GDP annually over the next several years given the Trump win. This could make other markets, India included, less appealing to FPIs.
On Thursday, the Bank of England had cut interest rates for the first time since the start of the pandemic.
The other major external reason that is influencing Indian markets is the expectations of a rate hike by the Bank of Japan, which may impact the yen carry-trade equation (carry trade involves investors using a high-yielding currency to fund a transaction involving a low-yielding currency). In August this year, when the BoJ raised rates to 0.25% from 0.1%, it resulted in unwinding of yen carry trade positions, leading to a crash in the Sensex and the Nifty. The Bank of Japan is expected to hike rates at their December meeting (18-19) as it is slated to consider uncertainties surrounding the new administration in the US. A weakening of the yen, as is the case now, could trigger a hike from the BoJ.

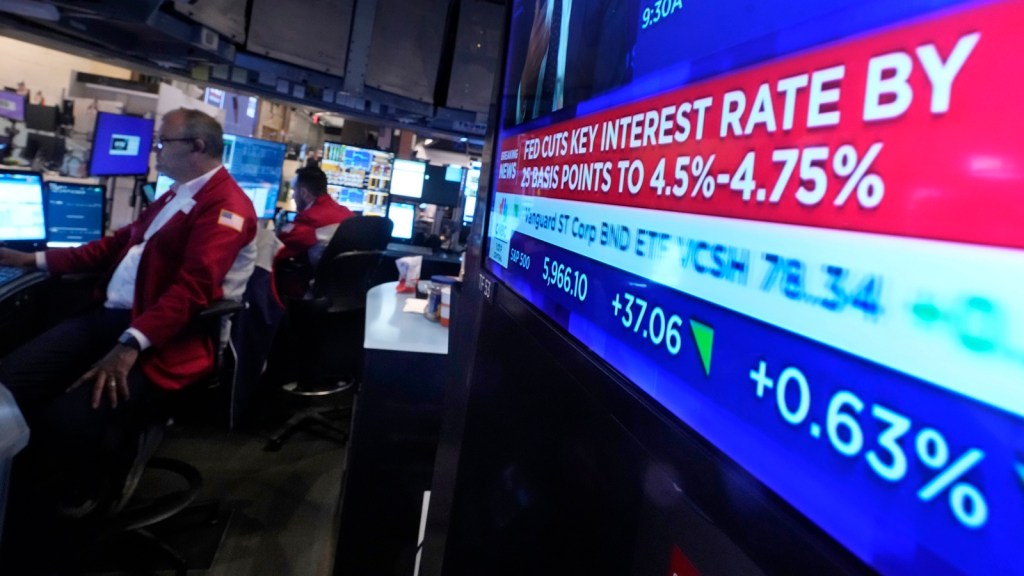 A screen at a trading post on the floor of the New York Stock Exchange displays the Federal Reserve interest rate decision. (Photo: AP)

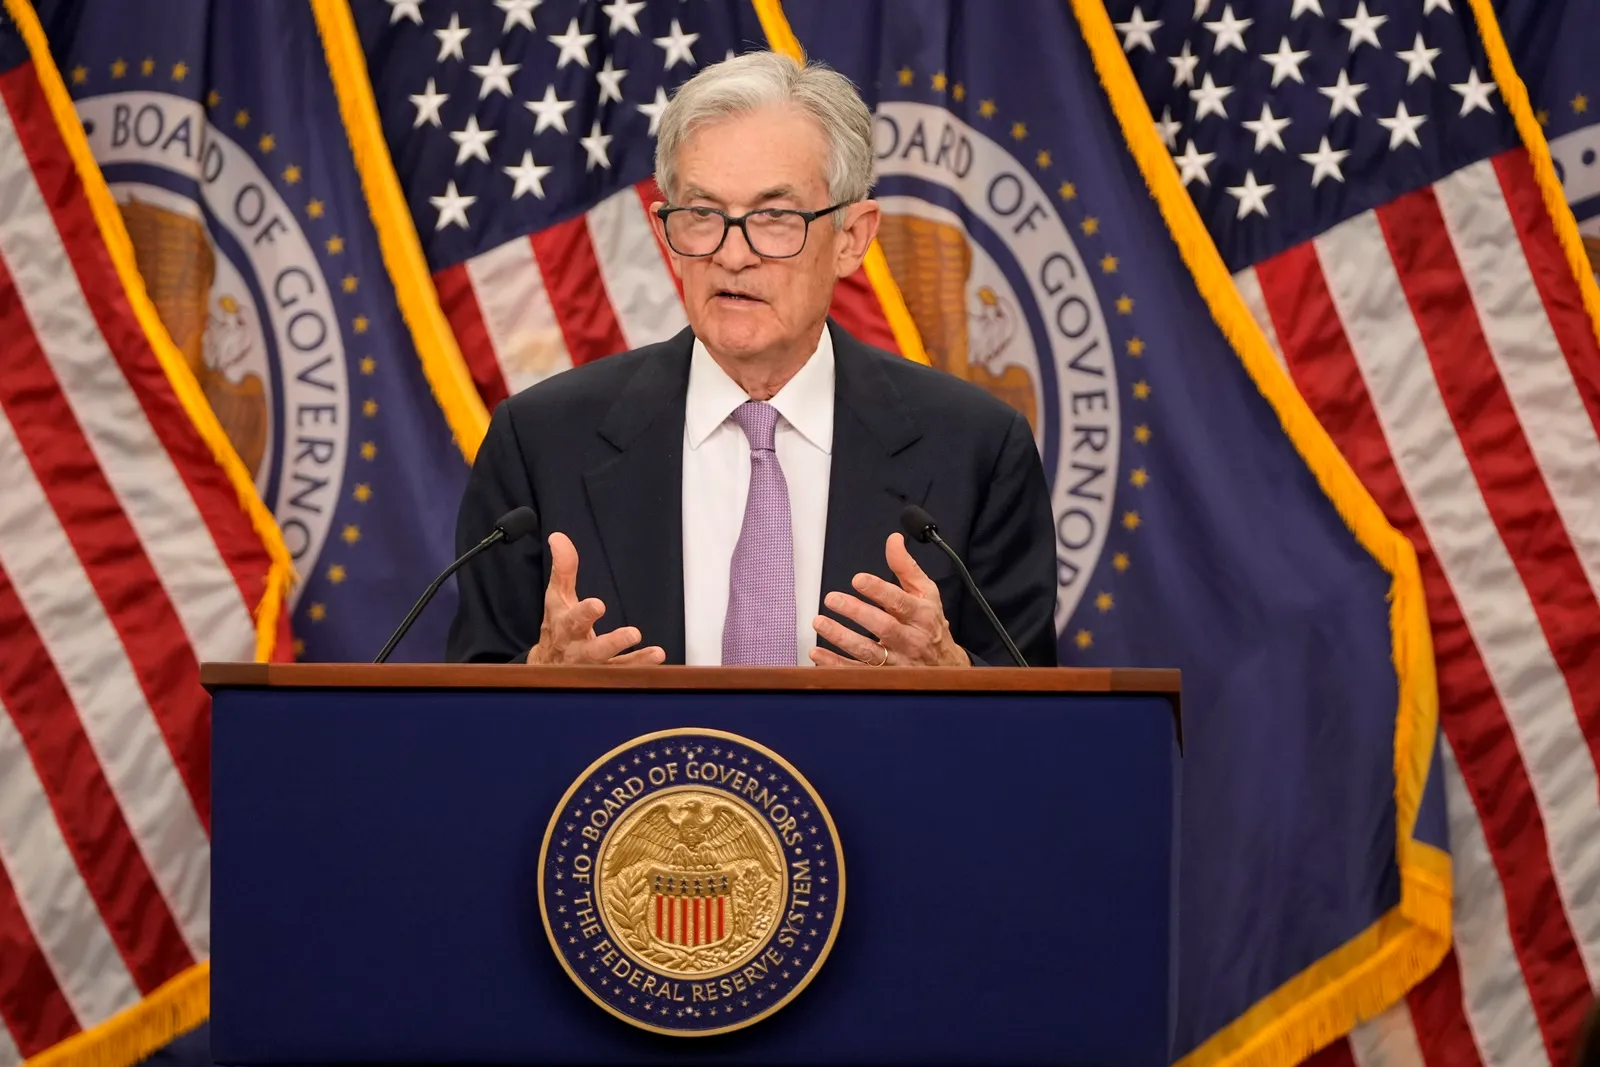 Federal Reserve Board Chairman Jerome Powell speaks during a conference at the Federal Reserve in Washington on Thursday. (Photo: AP)

 Share


