


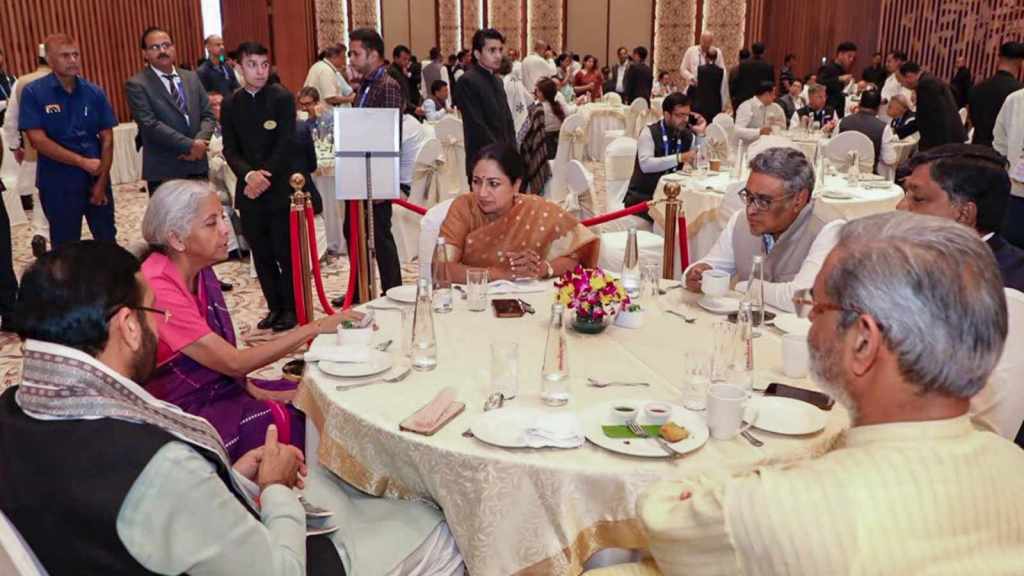
 In this image posted on Sept. 18, 2026, Finance Minister Nirmala Sitharaman, Delhi Chief Minister Rekha Gupta and others during a conference on 'Financing India's Journey towards Viksit Bharat', in New Delhi. (@CMODelhi/X via PTI Photo)
These were among several examples cited to highlight the export and growth potential that India has during the two-day conference of the Union Ministry of Finance with state finance ministers and finance secretaries on ‘Financing India’s Journey towards Viksit Bharat’ in Delhi.
Segmented land holdings, potential for higher agricultural exports, strain from gold holdings and imports, issues with logistical connectivity, focus on state-specific data collection and supply-chain constraints, also featured in the discussions as states and experts from academia and industry sat down for a brainstorming session on the journey ahead for the next two decades, three people aware of the discussions told The Indian Express.
The conference, a first-of-its-kind, focussed on discussing issues centred around agricultural transformation, energy transition with several state finance ministers putting forth their ground-level experiences in managing investments, logistics and efforts to boost exports in an open house session.
Union Finance Minister Nirmala Sitharaman was present in all the sessions.
Several state finance ministers and chief ministers talked about their state’s development plans and focus on energy transition.
For instance, Uttar Pradesh is learnt to have raised the high cost of the transition towards renewable energy and the need for more funds, while for West Bengal, which primarily relies on thermal power, the key concern was regarding the electricity tariff rates for industry players that cannot be lower than its neighbouring state that may be relying more on renewable power and offering a better tariff to the industry due to lower operational cost, a person aware of the discussions said.
Even as India is picking up pace with new global export destinations, the larger export share pie remains with China and this is learnt to have been underlined in the conference.
It was also discussed that to boost exports, the focus needs to be on specialised products and ensuring quality, a state government official who attended the meeting said.
There was also a discussion regarding the huge potential for raising farmer incomes and creating jobs. An example was provided of
how the French-fry potato farmers in Mehsana, Gujarat earn around Rs 1-3 lakh per hectare, while shrimp farmers earn Rs 5-8 lakh per hectare.
“There is room to scale up low-skill jobs for packers, sorters, graders and workers in the transport sector. It was discussed that mid-skill jobs can be targeted for ITI degree or food science degree holders, focusing on young men and women mostly from villages within 50-100 km of the factory,” another official said.
Financing of key infrastructure projects in states through private sector capital remained in focus. On the first day of the conference on Friday, Economic Affairs Secretary Anuradha Thakur had talked about the need for significant private sector investment to achieve India’s Viksit Bharat vision as government spending alone cannot meet the country’s massive financing requirements.
“We know that we meet today in the backdrop of ongoing global difficulties. Under these circumstances, and because of the scale of transformation we envisage towards ourselves to reach our shared goal, it needs to be borne in mind that this scale cannot be met solely by government budgets, and that private sector financing will need to play a critical role,” Thakur had said.
Going ahead, working groups, with participation from states, will take forward the thematic deliberations and identify sectoral financing requirements and actionable recommendations, the Secretary was quoted as saying in an official release.
Chief Economic Adviser V Anantha Nageswaran said while India’s savings base was substantial and would need to grow further, significantly greater participation by private capital would be essential to mobilise the investment required for Viksit Bharat.
NK Singh, President and Life Trustee, Institute of Economic Growth, and Fifteenth Finance Commission Chairman had stressed on the need for India’s gross domestic savings rate to rise to 38-40% from around 34% of GDP at present to sustain the 7-8% growth required for Viksit Bharat. He also called for state-wise debt sustainability assessments, and stressed greater fiscal transparency, including accounting for off-budget borrowings, guarantees, arrears and borrowings through state-owned entities.